All Categories
Featured
Guide to 2026 Chapter 13 Filing
Table of Contents
In submitting a chapter 11, the debtor presents a strategy to creditors which, if accepted by the lenders and approved by the court, will permit the debtor to restructure personal, financial or organization affairs and again end up being an economically productive individual or business.: Chapter 12 is developed for "family farmers" or "family anglers" with "regular annual income." It enables financially distressed family farmers and anglers to propose and carry out a plan to pay back all or part of their debts.
Generally, the strategy should offer payments over three years unless the court approves a longer period "for cause.": An individual with a routine earnings who is overcome by debts, however thinks such debt can be repaid within a reasonable time period, might file under chapter 13 of the bankruptcy code.
If the court authorizes the strategy, the debtor will be under the court's protection while paying back such debts. More info concerning the difference in between chapters can be discovered in the Personal Bankruptcy Fundamentals Handbook.
Many individuals in Michigan reach the point where they know they need relief, but they are stuck on one key question: should they file Chapter 7 or Chapter 13? Selecting the incorrect course can have real consequences for a house, an automobile, and a paycheck.
Navigating Bankruptcy Fees in 2026
You would like to know what these chapters would really do to your financial obligations, your credit, and your everyday life. You might have heard pals, colleagues, and even other legal representatives offer strong viewpoints about one chapter or the other, frequently without any mention of Michigan exemptions, regional trustees, or how your exact mix of financial obligations will drive the choice.
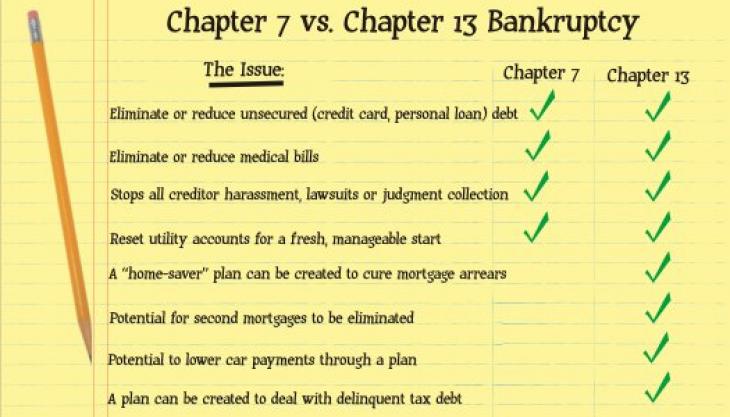
Both chapters come from federal law, but they do not play out the exact same way for every single filer. Hensel Law Workplace, PLLC regularly works with Michigan citizens to compare both chapters side by side utilizing genuine numbers, not generic checklists, and this article will show you how that analysis works and how to prepare for it.
When you file Chapter 7 in Michigan, an insolvency estate is developed that temporarily includes your non-exempt home, and a trustee is designated to evaluate your assets, income, and current financial history. In many Michigan cases, exemptions cover everything the individual owns, so the trustee does not sell anything, but that depends on your equity levels and the exemptions you use.Chapter 13 is different.
Significant Outcomes of Filing Personal BankruptcyHow to Stop Wage Garnishment Through 2026 Bankruptcy
Both chapters are submitted in the U.S.
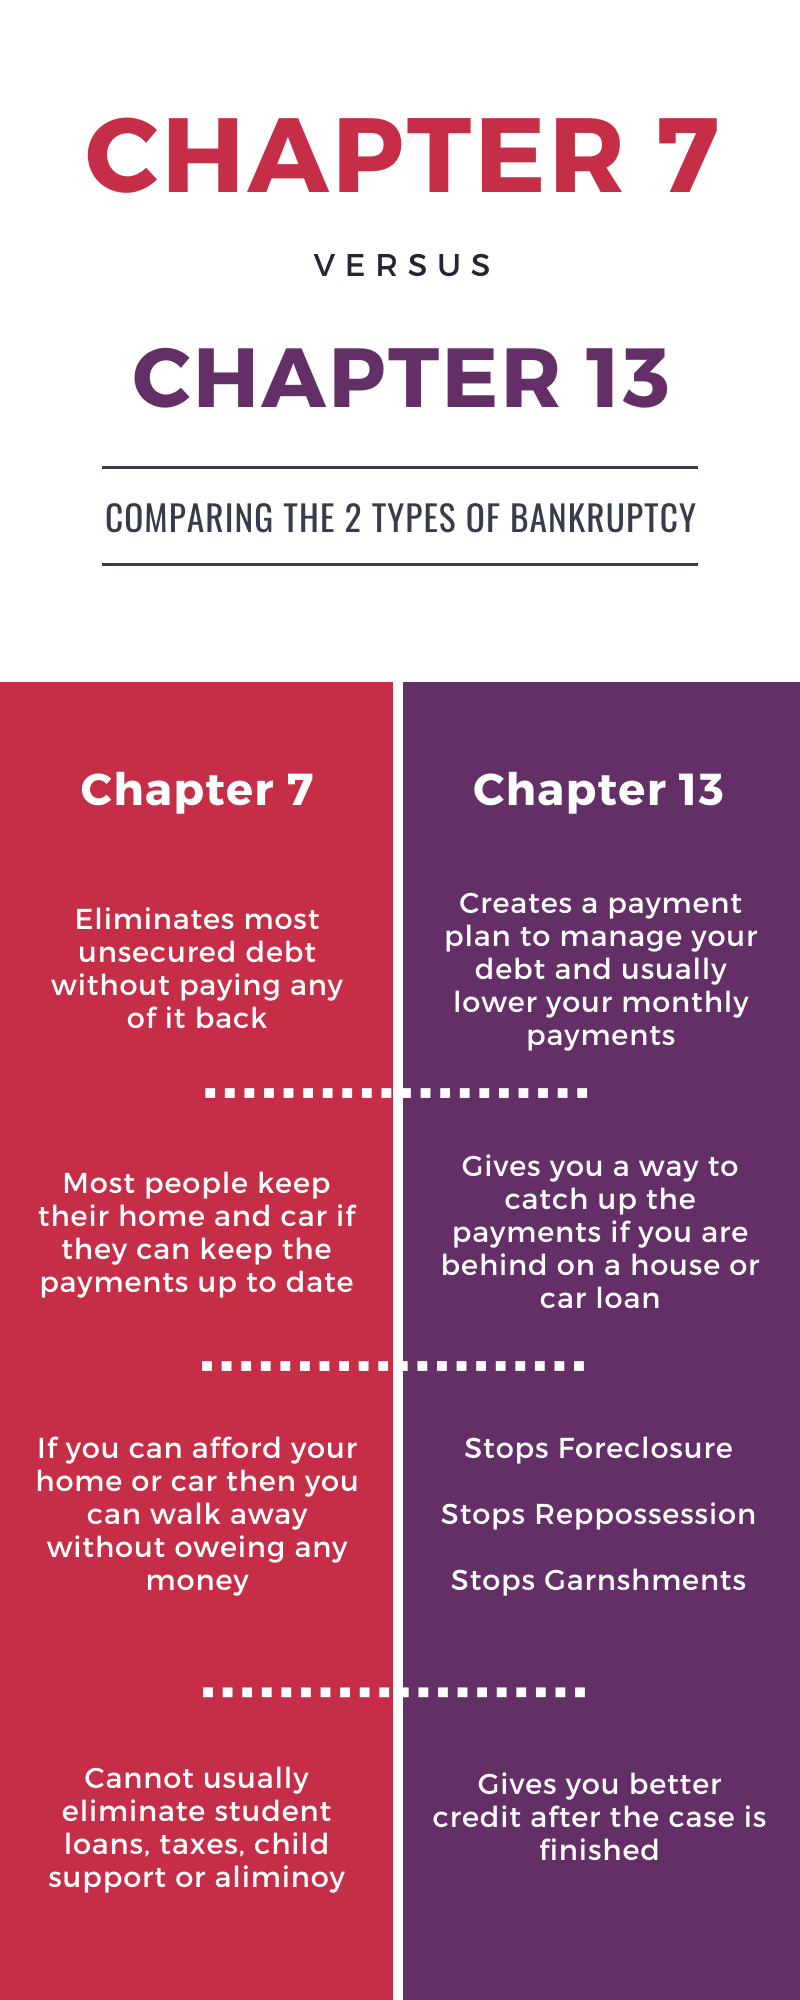
However, Nevertheless exemption rules, local trustee regional, and common local typical regional change how alter Chapter 7 is for your property and home realistic Chapter 13 payments are for your household. Because Hensel Law Office, PLLC deals with both Chapter 7 and 13 cases in Michigan, the objective is not to press everybody into one chapter, but to match the chapter to the filer's real situation.
The methods test compares your household earnings to the mean income level for a household of your size in Michigan and then changes for specific enabled costs. If your income is listed below the typical, you normally pass the methods test. If it is above, a more detailed computation of enabled expenses and debts determines whether a Chapter 7 filing would be presumed abusive.
You need to have a routine income, and your overall secured and unsecured financial obligations require to be within limits set by federal law. People typically wind up in Chapter 13 since their income is too high to comfortably pass the Chapter 7 means test, since they submitted a previous Chapter 7 too recently, or since they are behind on a mortgage or cars and truck loan and require a structured method to catch up.
Navigating Between Chapter 7 and 7 for 2026
In Michigan, household structure matters. A married person whose spouse is not submitting might still need to consist of some or all of the partner's earnings in the methods test, and that can impact whether Chapter 7 is readily available. It is also common for someone to technically get approved for both chapters from an earnings viewpoint, yet discover that their assets or debt mix make one choice plainly much safer.

Latest Posts

How to Initiate for Bankruptcy Efficiently in 2026
Key Updates in the Federal Bankruptcy Landscape
Long-Term Consequences of Filing