All Categories
Featured
Long-Term Impacts of 2026 Bankruptcy
Table of Contents
In submitting a chapter 11, the debtor presents a strategy to lenders which, if accepted by the financial institutions and authorized by the court, will allow the debtor to reorganize personal, monetary or business affairs and once again end up being a financially efficient individual or business.: Chapter 12 is developed for "household farmers" or "family fishermen" with "regular annual income." It allows economically distressed family farmers and fishermen to propose and perform a plan to pay back all or part of their debts.
Generally, the plan needs to provide for payments over three years unless the court authorizes a longer period "for cause.": A private with a routine income who is gotten rid of by financial obligations, however believes such financial obligation can be paid back within a reasonable duration of time, might submit under chapter 13 of the insolvency code.
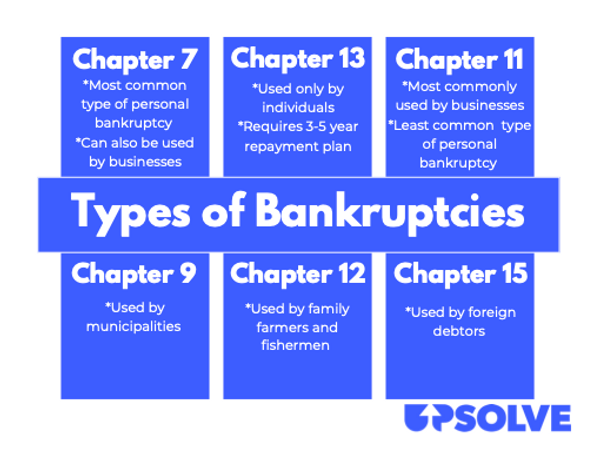
If the court approves the strategy, the debtor will be under the court's defense while repaying such debts. More info regarding the distinction between chapters can be discovered in the Personal Bankruptcy Basics Manual.
Being a couple of paychecks far from missing out on a home mortgage or cars and truck payment can keep anybody up during the night, specifically if collectors are currently calling or a wage garnishment has begun. Lots of people in Michigan reach the point where they know they need relief, however they are stuck on one essential concern: should they submit Chapter 7 or Chapter 13? Choosing the incorrect course can have genuine consequences for a home, a lorry, and an income.
How to File for Chapter 7 in 2026
You desire to understand what these chapters would in fact do to your financial obligations, your credit, and your day-to-day life. You might have heard buddies, colleagues, and even other attorneys give strong opinions about one chapter or the other, often with no reference of Michigan exemptions, local trustees, or how your specific mix of financial obligations will drive the choice.
Both chapters originate from federal law, but they do not play out the very same method for every filer. Hensel Law Office, PLLC routinely deals with Michigan residents to compare both chapters side by side using genuine numbers, not generic lists, and this post will show you how that analysis works and how to get ready for it.
When you submit Chapter 7 in Michigan, an insolvency estate is produced that momentarily includes your non-exempt residential or commercial property, and a trustee is selected to examine your assets, income, and recent financial history. In numerous Michigan cases, exemptions cover everything the person owns, so the trustee does not sell anything, however that depends upon your equity levels and the exemptions you use.Chapter 13 is various.
Calculating Bankruptcy Lawyer Costs for 2026Financial Support for 2026 Bankruptcy Filers
Both chapters are filed in the U.S.

However, Nevertheless exemption rules, guidelines trustee practices, and common local debt regional change how alter Chapter Dangerous is for your property and home realistic Chapter Reasonable payments are for your household. Due To The Fact That Hensel Law Office, PLLC handles both Chapter 7 and 13 cases in Michigan, the goal is not to push everybody into one chapter, however to match the chapter to the filer's real situation.
The means test compares your household earnings to the mean earnings level for a household of your size in Michigan and after that changes for certain permitted expenses. If your earnings is below the average, you typically pass the methods test. If it is above, a more comprehensive calculation of permitted expenditures and financial obligations identifies whether a Chapter 7 filing would be presumed violent.
You should have a regular earnings, and your total secured and unsecured financial obligations need to be within limits set by federal law. People often end up in Chapter 13 due to the fact that their income is expensive to conveniently pass the Chapter 7 indicates test, due to the fact that they submitted a previous Chapter 7 too recently, or because they lag on a home loan or vehicle loan and require a structured method to catch up.
Key Consequences of Filing Bankruptcy
In Michigan, household structure matters. A married person whose partner is not submitting might still require to include some or all of the spouse's earnings in the methods test, and that can affect whether Chapter 7 is offered. It is also common for somebody to technically receive both chapters from an earnings perspective, yet discover that their assets or financial obligation mix make one choice clearly safer.

Latest Posts

How to Initiate for Bankruptcy Efficiently in 2026
Key Updates in the Federal Bankruptcy Landscape
Long-Term Consequences of Filing