All Categories
Featured
Potential Consequences of Declaring Bankruptcy in 2026
Table of Contents
Say a staff member's non reusable incomes are $2,000.
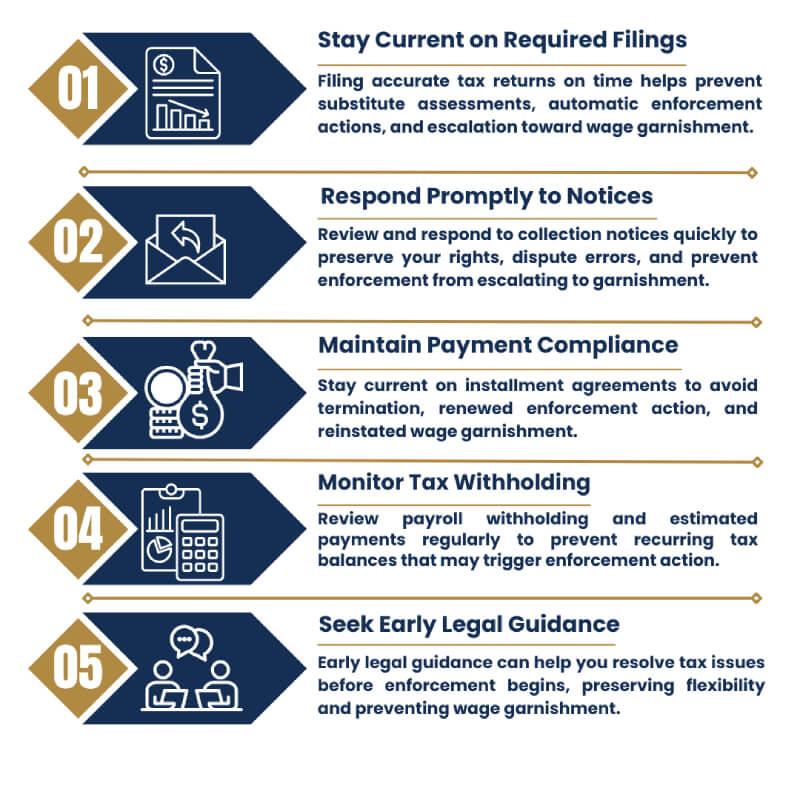
No. Under Title III of the Customer Credit Protection Act (CCPA), you can not release an employee whose incomes undergo garnishment However, the CCPA does not protect workers whose profits are subject to 2 or more garnishments. You should start garnishing an employee's wages when you get a student loan garnishment order.
Stop withholding if you receive a main notification. You can quickly establish a wage garnishment in Patriot's payroll software application. Remember that you are responsible for remitting garnishments to the appropriate agencies. You can learn how to set up a wage garnishment here.
Filing for Bankruptcy During 2026
The U.S. Department of Education (the Department) today announced that it will delay the application of involuntary collections on federal student loans, consisting of Administrative Wage Garnishment (AWG) and the Treasury Offset Program (TOP). The short-lived delay will make it possible for the Department to carry out major trainee loan repayment reforms under the Working Households Tax Cuts Act (the Act) to provide customers more choices to repay their loans.
The Act decreases the number of federal trainee loan repayment plans, getting rid of a complicated labyrinth of alternatives and making it much easier for borrowers to pick either a single basic repayment plan or income-driven payment (IDR) strategy that best fulfills their requirements. This includes a new IDR plan that waives unpaid interest for debtors with on-time payments whose payments do not fully cover accrued interest, which consists of small matching payments from the Department in specific scenarios to guarantee that exceptional principal is decreased monthly.
The delay in collections will give defaulted debtors additional time to assess these new repayment alternatives once they combine their loans or finish a repayment or rehabilitation contract. The Act likewise provides customers a 2nd possibility to rehabilitate a defaulted loan, permitting them to get their payments back on track and get the loan out of default.
The hold-up in collections will provide defaulted customers extra time to start the rehab procedure, consisting of the capability to restore their loan a second time.
The Trump administration will resume garnishing salaries from student loan customers in default in early 2026, the U.S. Education Department verified to NPR. The relocation comes after a years-long time out in wage garnishment due to the pandemic. "We anticipate the first notifications to be sent to roughly 1,000 defaulted borrowers the week of January 7," a department representative informed NPR.
Comparing Chapter 7 and Reorganizing FilingsBankruptcy Support to Halt Garnishments
A customer remains in default when they have actually not made loan payments in more than 270 days. Once that occurs, the federal government can attempt to collect on the debt by taking tax refunds and Social Security benefits, and likewise by ordering a company to keep as much as 15% of a debtor's pay.
Betsy Mayotte, the president and founder of The Institute of Student Loan Advisors, states even though borrowers have actually anticipated this, the timing is unfortunate. "It will coincide with the increase in health care costs for a lot of these defaulted customers," she stated, referring to the premium increases for Affordable Care Act medical insurance that kick in in 2026.
Picking Chapter 7 for Your 2026 BenefitAnother 3.7 million are more than 270 days late on their payments and 2.7 million remain in the early phases of delinquency. "We've got about 12 million debtors today who are either delinquent on their loans or in default," Preston Cooper, who studies student loan policy at AEI, told NPR.
Choosing Between Chapter 7 and Chapter 13
Cory Turner contributed to this story.
(Article Updated Jan. 6 and 8, 2026) This short article notes federal and state consumer law changes set up to go into result or expire throughout the period from December 1, 2025, through January 1, 2027. Other customer law modifications will be enacted in 2026 and will go into result in 2026; this post notes modifications whose reliable dates have actually already been scheduled as of December 31, 2025.

Latest Posts

How to Initiate for Bankruptcy Efficiently in 2026
Key Updates in the Federal Bankruptcy Landscape
Long-Term Consequences of Filing