All Categories
Featured
Potential Legal Impacts of 2026 Bankruptcy
Table of Contents
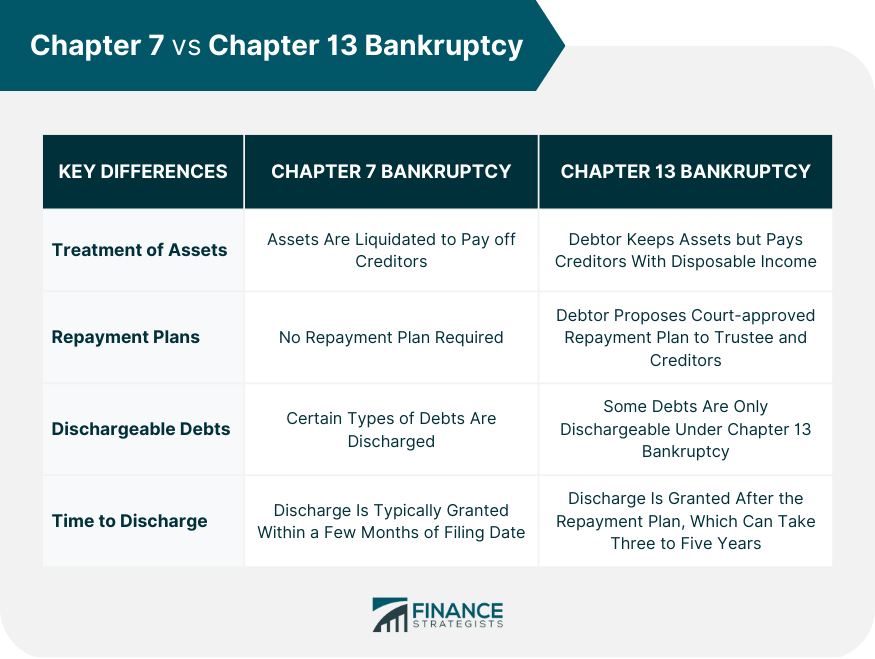
In Chapter 7, the trustee looks at your properties and compares their equity to the exemptions you declare. Equity is the value of the home minus what you owe on it. If your equity in a home, lorry, or other property is fully covered by exemptions, the trustee typically leaves that possession alone.
That analysis often figures out whether Chapter 7 is safe for somebody with built-up equity in Michigan property or a paid-off car. In Chapter 13, exemptions still matter, however in a different method. Rather of offering non-exempt property, the law generally needs that unsecured creditors receive at least as much through your strategy as they would have received if you filed Chapter 7 and your non-exempt possessions were offered.
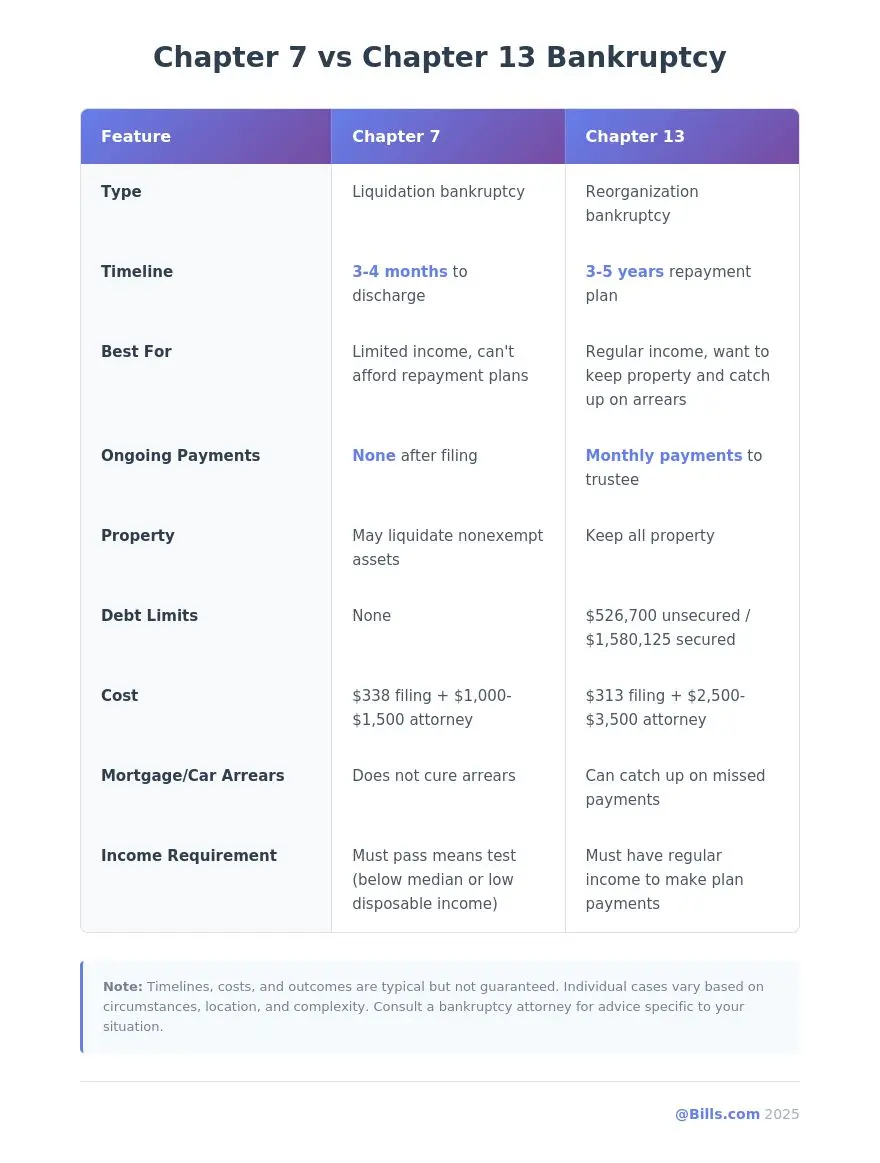
For instance, a Michigan property owner with equity above the homestead exemption might pick Chapter 13, make a greater monthly payment for a set variety of years, and still keep your home. Due to the fact that the choice in between Michigan and federal exemptions can tilt the balance between Chapter 7 and 13, this is not something to think at.
If Chapter 7 looks risky but the customer's income can support a practical Chapter 13 payment, the suggestion might move towards Chapter 13 to protect hard-earned residential or commercial property. How each chapter treats your particular financial obligations frequently matters more than any abstract benefits and drawbacks list. Unsecured debts, such as charge card, medical costs, payday advance, and numerous personal loans, normally get comparable outcome in both chapters, but through various courses.
In Chapter 13, unsecured creditors frequently get a share of what you pay into the strategy, which might be anywhere from a little portion to the full amount, and the staying balance can be discharged at the end if you finish your strategy. Protected debts include residential or commercial property that works as collateral, such as a home loan on a home or a lien on an automobile.
Expert Bankruptcy Support Resources for 2026 DebtorsSaving Income From 2026 Bankruptcy Garnishment
Keeping a protected property frequently involves staying current on payments and, sometimes, signing a reaffirmation contract that keeps you personally accountable on that specific loan after insolvency. If you are far behind and can not capture up quickly, surrendering the property in Chapter 7 wipes out your individual liability for any deficiency balance after the loan provider offers it.
You can expand home mortgage or auto loan financial obligations over a three to five-year plan, which is called treating defaults, while likewise resuming your routine monthly payments. In some situations, Chapter 13 likewise permits a reduction of certain car loan balances to the cars and truck's current worth, a principle called cramdown, though in-depth guidelines use.
Top priority and nondischargeable debts, such as recent income taxes, child support, alimony, and the majority of student loans, stand in a different category. These are generally not eliminated in Chapter 7, though the automated stay can pause some collection while the case is pending. In Chapter 13, these financial obligations are frequently paid in complete through your strategy before unsecured financial institutions get anything.
At Hensel Law Workplace, PLLC, a detailed creditor list is mapped to these classifications so you see precisely which financial obligations will be erased, which need to be paid, and which chapter handles them more successfully. Knowing the length of time each chapter lasts and what life looks like throughout the case can make the decision feel less abstract.
Is Chapter 13 the Best Relief in 2026?Shortly after filing, the automated stay normally stops garnishments, lawsuits, and most collection calls. You participate in a conference of financial institutions, frequently called the 341 meeting, where the trustee asks concerns about your paperwork and finances. After that, you generally wait on deadlines to pass and for the court to release a discharge, unless the trustee needs more information or is checking out non-exempt properties.
Picking Chapter 7 for Your 2026 Benefit
You submit the case, and the automated stay enters into impact, stopping garnishments, foreclosure sales, and the majority of collection activity. You propose a payment plan, begin making monthly payments to the Chapter 13 trustee, and go to a 341 meeting and, in lots of cases, a confirmation hearing where the judge thinks about whether to approve the strategy.
Lots of Michigan filers are shocked by how structured however workable the everyday reality can be when the strategy is sensible. In Chapter 7, your main obligations are to be truthful, provide files, attend your conference, and complete a required monetary education course. In Chapter 13, the included obligations consist of adhering to a budget plan, making every strategy payment on time, and reporting considerable earnings modifications.
As soon as you understand how each chapter works, the next action is lining that up with your goals. One core tradeoff is speed versus structure. Chapter 7 relocations much faster and typically involves no long-lasting payment commitments, which interest Michigan occupants and property owners who are present on their home mortgages and have mainly unsecured financial obligations.

Latest Posts

How to Initiate for Bankruptcy Efficiently in 2026
Key Updates in the Federal Bankruptcy Landscape
Long-Term Consequences of Filing